
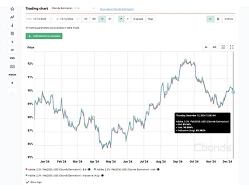
Explore bonos aplicando más de 50 filtros avanzados (calificación, rentabilidad, precio y más)
Solicite su accesoExplore la más completa base de datos
1 000 000
bonos
100 000
acciones
175 910
ETF & Funds
100 000
índices
Siga su portfolio de la manera más eficiente

Explore bonos aplicando más de 50 filtros avanzados (calificación, rentabilidad, precio y más)
Solicite su acceso


 Bond Screener
Perspectiva Semanal
Global risk tone softened as equities were broadly lower in USD and volatility stayed contained (VIX 14.8). The peso weakened to 17.22/USD (+1.5% w/w); Mexico’s IPC fell 0.86% while the S&P 500 edged −0.08%. Rates moved higher in the U.S. (10Y at 5.00%), and Mexico’s 10Y MBono closed at 9.42% with the 10Y MBono–UST spread at 442 bp; both UST and MBono curves remain steep. Mexico and U.S. breakevens are inverted across maturities. Mexico’s 5Y CDS trades at 79 bp; Pemex at 225 bp. WTI is $99, leading commodities YTD.
The week focuses on Mexico’s inflation print Thursday as a key gauge of price pressures, alongside Banxico’s rate decision (consensus 6.5%), July IGAE, and August unemployment. U.S. releases include September PMIs, jobless claims, new home sales, and final University of Michigan sentiment. The UK and Eurozone publish flash PMIs, with Eurozone M3 on Friday; Japan posts its manufacturing PMI. Fed funds futures imply 3.2 cumulative 25 bp hikes by Oct-27, lifting the implied rate from 3.64% to 4.70%.